
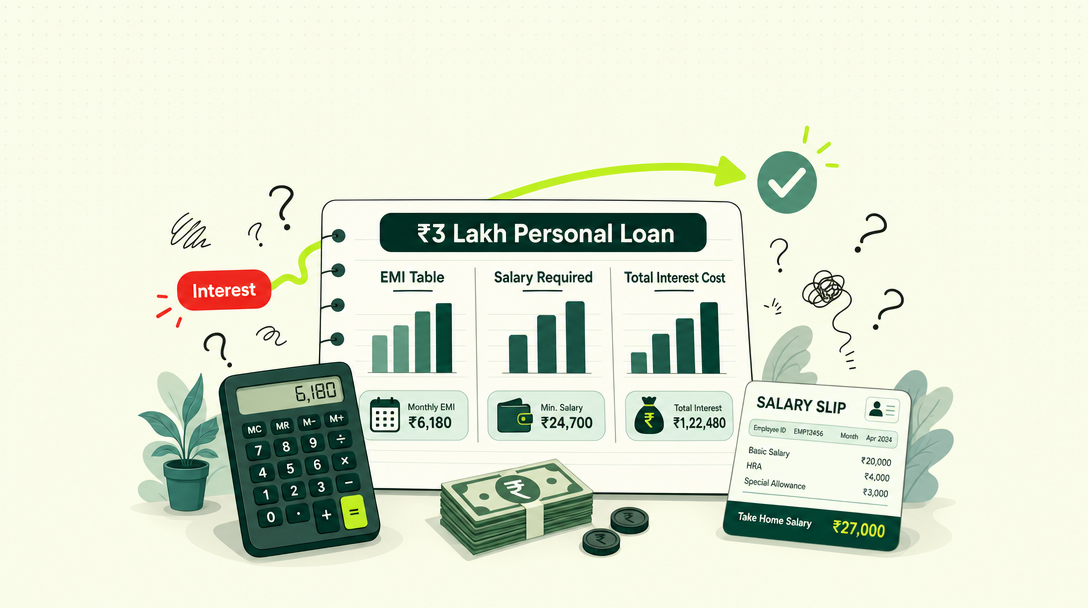
Three lakh rupees is one of the most common personal loan amounts in India. It is enough for a wedding contribution, a medical bill, a home repair,r or clearing several credit cards, and small enough that most salaried borrowers qualify without collateral.
The amount is fixed. What varies is the rate you are offered and the tenure you choose, and together they decide whether you pay ₹35,000 or ₹1.5 lakh in interest. This guide gives you the full EMI table, the salary lenders look for, and the specific choices that bring the total cost down.
₹3 lakh personal loan EMI table
EMIs below use the standard reducing-balance formula and are rounded to the nearest rupee.
| Interest rate | 1 year | 2 years | 3 years | 4 years | 5 years |
|---|---|---|---|---|---|
| 11% | ₹26,514 | ₹13,982 | ₹9,822 | ₹7,754 | ₹6,523 |
| 13% | ₹26,795 | ₹14,263 | ₹10,108 | ₹8,048 | ₹6,826 |
| 16% | ₹27,219 | ₹14,689 | ₹10,547 | ₹8,502 | ₹7,295 |
| 20% | ₹27,790 | ₹15,269 | ₹11,149 | ₹9,129 | ₹7,948 |
| 24% | ₹28,368 | ₹15,861 | ₹11,770 | ₹9,781 | ₹8,630 |
Two patterns are worth noticing. Moving from one year to two halves the EMI, but each additional year saves less. And at longer tenures, the interest rate starts to matter more than the tenure.
If your lender quotes a flat rate rather than a reducing rate, these figures do not apply. A flat rate of 10% costs far more than 10% reducing; see flat vs reducing interest rate.
Total interest: how rate and tenure change the cost
| Scenario | EMI | Total interest |
|---|---|---|
| 13%, 2 years | ₹14,263 | ₹42,301 |
| 13%, 3 years | ₹10,108 | ₹63,895 |
| 13%, 5 years | ₹6,826 | ₹1,09,555 |
| 11%, 3 years | ₹9,822 | ₹53,578 |
| 20%, 3 years | ₹11,149 | ₹1,01,367 |
Stretching the same 13% loan from three to five years lowers the EMI by ₹3,282 but adds ₹45,660 in interest. Getting 11% instead of 20% over three years saves ₹47,789. The rate you qualify for is worth as much as the tenure you choose.
Salary required for a ₹3 lakh loan
Lenders typically allow your total EMIs to reach 40% to 50% of net monthly income. With no other loans, the minimum salary for a ₹3 lakh EMI works out as below.
| Loan terms | EMI | Salary needed at 50% FOIR | Salary needed at 40% FOIR |
|---|---|---|---|
| 13%, 3 years | ₹10,108 | ₹20,216 | ₹25,270 |
| 13%, 5 years | ₹6,826 | ₹13,652 | ₹17,065 |
| 20%, 3 years | ₹11,149 | ₹22,298 | ₹27,873 |
Most banks also set a minimum income of ₹15,000 to ₹25,000. In practice, a net salary of ₹25,000 or more with no other EMIs makes a ₹3 lakh loan over three years comfortable for most lenders. Existing EMIs raise the salary needed one-for-one; our guide to a personal loan on a ₹30,000 salary shows how.
The processing fee and your real interest rate
Most lenders charge a processing fee of 1% to 3%, plus 18% GST, deducted from the disbursal.
On a ₹3 lakh loan with a 2% fee, you pay ₹7,080 and receive ₹2,92,920, but repay EMIs calculated on the full ₹3 lakh. At a quoted 13% over three years, the effective annual cost rises to about 14.7%.
This is why the Key Fact Statement shows the Annual Percentage Rate (APR), which includes fees. Compare offers on APR, not headline rate. Our KFS and APR guide explains how to read it.
Eligibility and documents
Typical eligibility for salaried applicants:
- Age 21 to 58 or 60 at loan maturity
- Net monthly income of ₹15,000 to ₹25,000 and above, depending on lender and city
- At least six months to a year with the current employer
- CIBIL score of 700 or more, with 750+ needed for the best rates
Typical documents: PAN, Aadhaar, the last three months’ salary slips, six months of bank statements, and employment proof. Many digital lenders verify income through account aggregator consent instead of uploaded statements.
How to reduce the total cost
- Raise your score before applying. Clearing card balances a month before applying can move you into a lower rate band.
- Pick the shortest tenure your budget supports. A three-year tenure costs about ₹45,000 less than five years at 13%.
- Negotiate the processing fee. Many lenders reduce or waive fees for strong profiles or during campaigns.
- Decline bundled insurance you do not need. It is optional and adds to the effective cost.
- Check prepayment terms. Fixed-rate personal loans may carry foreclosure charges; a lender that allows free partial prepayment gives you flexibility.
- Compare several offers through soft checks rather than applying to many lenders at once.
Alternatives worth comparing
- Top-up on an existing home loan, often at a much lower rate if you have one
- Loan against FD, typically 1 to 2 percentage points above the FD rate
- Credit card loan, fast if pre-approved, but compare the rate carefully; see credit card loan vs personal loan
- ₹5 lakh loan at a better rate, if you need more soon; larger loans sometimes price lower, as covered in our ₹5 lakh personal loan guide
Use cases
Kavya earns ₹38,000 net and has no loans. She needs ₹3 lakh for her brother’s wedding. Offered at 12.5% over three years, her EMI of about ₹10,036 is 26% of her income, well within limits. She chooses three years over five and saves roughly ₹43,000 in interest.
Imran has ₹2.7 lakh spread across three credit cards at 42% annual interest. He takes a ₹3 lakh personal loan at 14% for three years, clears the cards, and keeps ₹30,000 as a buffer. His monthly outgoings fall, and his credit utilization drops to near zero.
Key takeaways
- A ₹3 lakh personal loan costs ₹10,108 a month over three years at 13%, with ₹63,895 in total interest.
- The difference between 11% and 20% over three years is about ₹48,000 in interest.
- Extending from three to five years at 13% cuts the EMI by ₹3,282 but adds about ₹45,700 in interest.
- A net salary of around ₹25,000 with no other EMIs typically supports this loan over three years.
- A 2% processing fee lifts a 13% loan’s effective cost to about 14.7%, so compare offers on APR.
Frequently asked questions
At 11%, ₹9,822; at 13%, ₹10,108; at 16%, ₹10,547; and at 20%, ₹11,149.
With no other EMIs, a net salary of about ₹20,000 to ₹25,000 supports a three-year loan at 13%. A five-year tenure lowers the requirement to roughly ₹14,000 to ₹17,000.
Some NBFCs lend at that score, usually at 18% or higher and sometimes for a smaller amount. A few months of improvement can save tens of thousands in interest.
Three years, if the EMI keeps your total obligations under about 40% of take-home pay. Five years costs roughly ₹45,000 more at 13%.
Pre-approved offers can disburse the same day. New-to-lender applications typically take one to three working days after documents are verified.
Conclusion
A ₹3 lakh loan is easy to get and easy to overpay for. The difference between a careful borrower and a hurried one is often ₹40,000 to ₹70,000 over the life of the loan. Compare APRs, pick the shortest affordable tenure, and let your credit score do the negotiating.
Compare ₹3 lakh personal loan offers from multiple lenders on TapTap Loans.